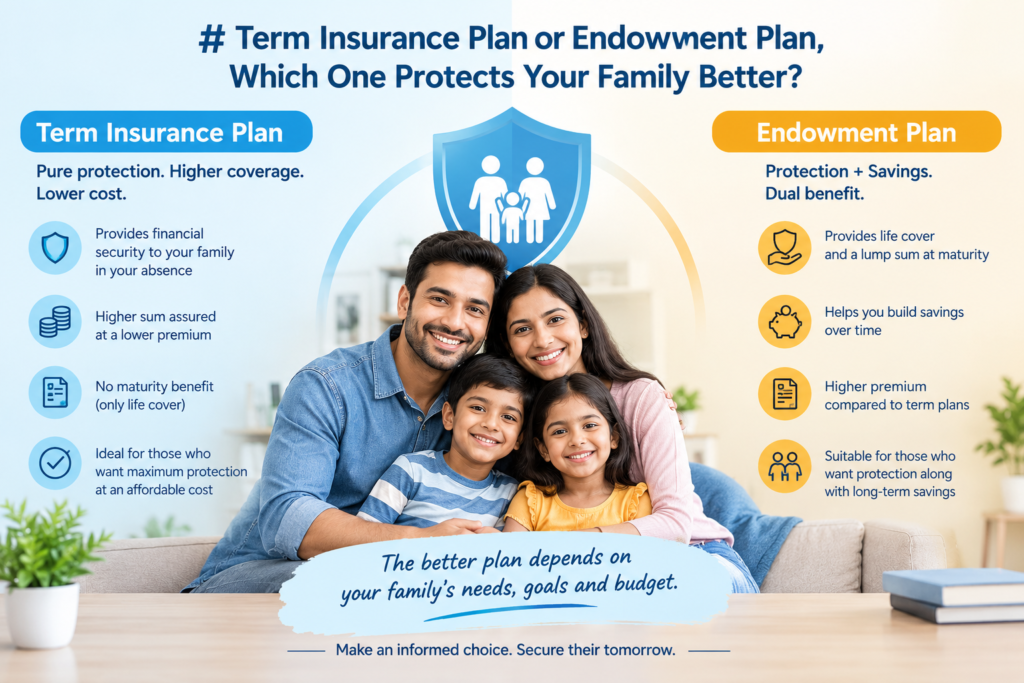
A term insurance plan and an endowment plan both provide life cover, but they are designed for different financial needs. A term plan focuses mainly on protection for a fixed period, while an endowment plan combines life cover with a savings element and may provide a maturity amount.
This difference affects the premium, amount of cover and benefits available to the policyholder. Understanding how each plan works can help a family choose insurance based on its financial priorities rather than only comparing premiums.
What is a term insurance plan?
A term insurance plan provides life cover for a specified period. The policyholder pays premiums according to the policy terms.
If the life insured dies during the policy term and the claim is payable, the nominee receives the applicable death cover.
A standard term plan generally does not provide a maturity payout if the life insured survives the full policy term. This makes it primarily a protection product, with the premium focused on providing life cover.
For example, a person may choose a 25-year term plan with Rs. 1 crore of death cover to provide financial protection to dependants during their working years.
What is an endowment plan?
An endowment plan combines life cover with a savings element.
If the life insured dies during the policy term, the nominee receives the applicable death cover according to the policy terms. If the policyholder survives until maturity, the policy may provide a maturity amount based on its terms.
Understanding what is endowment plan is helps you learn how life insurance combines financial protection with savings, offering life cover and a maturity benefit to support long-term financial goals.
Some endowment plans may also provide bonuses, depending on the type of policy and applicable declarations.
Because an endowment plan combines protection with savings, its premium can be higher than that of a term plan for a similar level of life cover.
How do term and endowment plans differ?
The biggest difference is their main purpose.
A term insurance plan is generally suitable when the priority is higher life cover for financial protection. An endowment plan may be considered when the policyholder also wants a savings component within the insurance policy.
The main differences include:
- Purpose: Term plans focus mainly on protection, while endowment plans combine protection and savings.
- Maturity: A standard term plan generally has no maturity payout, while an endowment plan may provide one.
- Premium: A term plan generally costs less for a similar amount of life cover.
- Savings element: A standard term plan does not have a savings component, while an endowment plan does.
- Death cover: Both can provide death cover, subject to the respective policy terms.
IRDAI’s life insurance product framework recognises protection and savings as different product categories, reflecting these distinct purposes.
Which plan can provide higher life cover?
For the same premium budget, a term insurance plan will generally allow a person to choose a higher amount of life cover than an endowment plan.
This is because a term plan is structured primarily for protection, while an endowment plan also includes a savings component.
For a family with significant financial responsibilities, such as a home loan, children’s education costs or dependants relying on one income, the amount of life cover can therefore be an important consideration.
However, the required cover should be assessed based on income, liabilities, existing assets and the family’s financial needs rather than using premium alone as the deciding factor.
What happens when the policyholder survives?
If a standard term insurance plan reaches the end of its policy term and the life insured has survived, the policy generally ends without a maturity payout.
An endowment plan, on the other hand, may provide a maturity amount when the policyholder survives the full term, according to the policy conditions.
For example, a person choosing an endowment plan for a 20-year financial goal should check the projected and guaranteed components of the maturity value, along with the premium commitment and policy conditions.
A maturity amount shown in an illustration should not automatically be treated as a guaranteed return unless the policy specifically states that it is guaranteed.
Which plan should a family consider?
A term insurance plan may be considered when the main objective is to protect dependants against the financial impact of losing the policyholder’s income.
What is an endowment plan? An endowment plan is a type of life insurance policy that combines life cover with a savings component. It typically pays a maturity benefit if the policyholder survives until the end of the policy term, subject to the policy’s terms and conditions. If the policyholder passes away during the policy term, a death benefit is generally payable to the nominee.
An endowment plan may be considered when the policyholder wants life cover along with a structured savings component and can maintain the required premium payments for the policy term.
These products can also serve different purposes within a broader financial plan. For example, a family may use term insurance for income protection while using separate investments or savings products for education and other financial goals.
The important point is not to choose an endowment plan only because it offers a maturity amount or a term plan only because its premium is lower. Compare the coverage, premiums, benefits, policy duration and conditions to determine which option suits your financial needs.
What should you check before choosing?
Before selecting either plan, consider these factors:
- Required life cover: Estimate the financial support your dependants would need.
- Premium affordability: Make sure the premium can be maintained throughout the required period.
- Policy term: Match the term with major financial responsibilities such as children’s education or outstanding loans.
- Maturity benefit: For an endowment plan, understand what is guaranteed and what depends on bonuses or other policy conditions.
- Early exit: Check the policy’s surrender, paid-up and discontinuance provisions before committing to a long-term policy.
- Tax treatment: Check the tax rules applicable to the specific policy, issue date and type of payout.
What are the tax considerations?
Tax treatment can differ between premiums, death claims and maturity amounts.
Under the Income Tax Act, 2025, qualifying amounts received under a life insurance policy may be excluded from total income under Section 11 read with Schedule II, subject to the conditions specified in the law. The rules also contain specific conditions for certain policies based on factors such as the policy issue date, premium and sum assured.
Therefore, the tax treatment of an endowment maturity amount should not simply be assumed from the product name. The specific policy and applicable tax-year rules should be checked.
Which option is more suitable for family protection?
If the primary concern is providing substantial financial protection to dependants during the policyholder’s earning years, a term insurance plan can be considered because it is designed mainly for life cover.
If the policyholder wants life cover along with a savings component and is comfortable with the associated premium commitment, an endowment plan may be considered.
The two products should therefore be compared based on cover required, premium, policy duration, maturity provisions and financial goals, rather than only on the amount paid or received.
Conclusion
A term insurance plan and an endowment plan serve different purposes. A term plan focuses mainly on financial protection and generally provides a higher amount of life cover for a given premium, while an endowment plan combines life cover with a savings element and may provide a maturity amount.
The right choice depends on the family’s protection needs, budget, financial commitments and long-term goals. Checking the policy terms, premium commitment, maturity provisions and applicable tax rules can help a policyholder make a more informed decision.