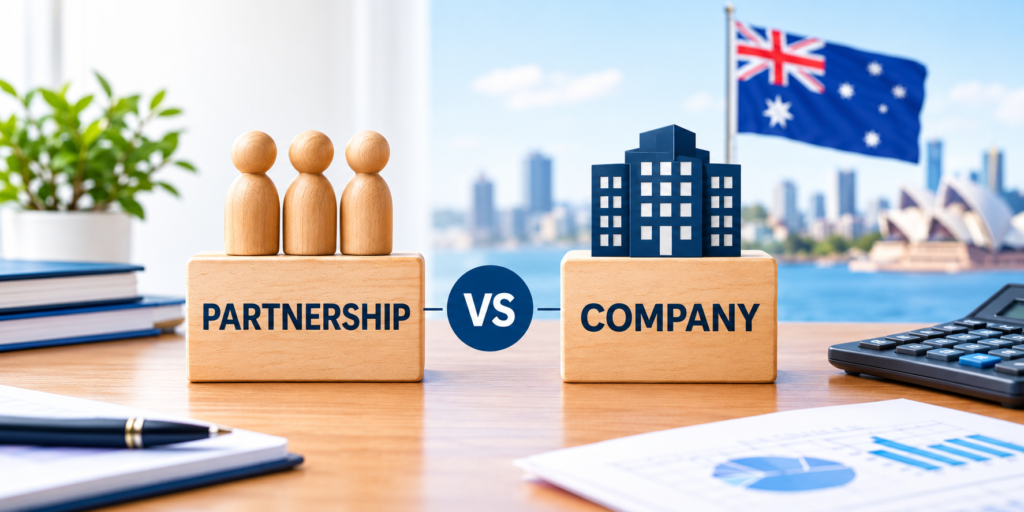
Choosing a business structure is one of those decisions that can look simple at first and become much more important as the business grows. In Australia, partnerships and companies are both common structures, but they handle income, tax and reporting quite differently.
Understanding these differences before registering a business can help owners avoid unexpected tax obligations and make better long-term plans. The right structure depends on factors such as business income, risk, ownership, future growth and how profits will be used.
How Is a Partnership Taxed in Australia?
A partnership is generally formed when two or more people run a business together and share its income or losses. The partnership itself does not generally pay income tax on its profits.
Instead, the partnership lodges an annual tax return showing its income, deductions and how the income or loss is divided between the partners. Each partner then reports their share in their own individual tax return.
For example, imagine two people operate a small consulting business and agree to split profits equally. If the partnership makes a taxable profit of $100,000, each partner would generally include their $50,000 share in their individual tax return, subject to the applicable tax rules.
This flow-through treatment is one of the main differences between a partnership and a company.
How Is a Company Taxed?
A company is a separate legal entity from its owners. The business earns income in its own name and is responsible for its own tax obligations.
A company must lodge its own annual company tax return and generally pays tax on its taxable income. The money earned by the company belongs to the company rather than automatically belonging to its shareholders personally.
Company tax rates can differ depending on whether the company qualifies for the applicable lower company tax rate. Current rates and eligibility requirements should always be checked against Australian Taxation Office guidance because tax rules can change.
Owners also need to understand that taking money from a company is not the same as simply withdrawing partnership profits. Payments to directors or shareholders can have specific tax and reporting consequences.
Partnership vs Company Tax: The Main Differences
The biggest difference is how business profits are taxed.
With a partnership, the partnership generally does not pay income tax itself. The partners are taxed on their respective shares of the partnership’s taxable income.
With a company, the company is a separate taxpayer and pays tax on its taxable income. Shareholders may then have additional tax considerations when they receive payments such as dividends.
There are also differences in administration. Partnerships generally have fewer ongoing legal and reporting requirements than companies. Companies have additional obligations because they are separate legal entities and are subject to corporate rules and ASIC requirements.
What About Business Losses?
Business losses are another area where the structure matters.
A partnership records its losses and allocates them between partners according to the partnership arrangement and relevant tax rules. Whether a partner can use a partnership loss against other income depends on the circumstances and applicable legislation.
Companies generally retain their tax losses within the company rather than simply passing those losses directly to shareholders. There are specific rules governing how companies can use carried-forward tax losses.
This is one reason why businesses expecting fluctuating income should consider the long-term tax implications of their structure rather than looking only at the current financial year.
Partnership or Company: What About Liability?
Tax is important, but it should not be the only consideration.
In a general partnership, partners can have unlimited liability for partnership debts and obligations. This means personal assets may be exposed to business liabilities in certain circumstances.
A company is a separate legal entity, and shareholders generally have limited liability. However, directors still have legal responsibilities and can be personally liable in particular situations, including certain breaches of their duties.
For a business carrying significant financial or commercial risk, this distinction deserves careful consideration.
Which Structure Is Better for a Growing Business?
There is no universal answer. A partnership may suit people who want a relatively straightforward structure and are comfortable sharing management, profits and responsibilities.
A company may be considered by businesses planning for expansion, bringing in investors or retaining profits within the business. It can also provide a different level of legal separation between the business and its owners.
However, setting up a company usually involves more administration, record keeping and ongoing compliance.
Business owners should therefore look beyond headline tax rates. The overall cost of compliance, accounting, legal obligations, asset protection and future plans can all influence the decision.
Can You Change From a Partnership to a Company?
Yes, businesses can change their structure as they develop. Moving from a partnership to a company can have tax, legal and administrative consequences, so it should not be treated as a simple registration change.
The Australian Government notes that a partnership cannot simply be converted directly into a company. Generally, a new company needs to be established and the partnership dealt with separately. Tax and legal advice is recommended before making the change.
If your business is already operating as a partnership, getting advice from a partnership tax return accountant can help you understand your current obligations and prepare accurate partnership and individual tax reporting.
What Should Business Owners Consider Before Choosing?
Before settling on a structure, consider:
- Expected business income and profit levels
- Whether profits will be distributed or retained
- Potential business risks and liabilities
- Number of owners and how decisions will be made
- Administrative and compliance costs
- Future plans for investment or expansion
- Tax treatment of business losses
- What happens if a partner or shareholder leaves
- Whether the structure may need to change later
Tax should be viewed as one part of the wider business structure decision.
Final Thoughts
Partnership and company structures can both work well for Australian businesses, but their tax treatment is fundamentally different. A partnership generally passes taxable income through to its partners, while a company is a separate taxpayer responsible for its own company tax obligations.
As a business grows, the structure that once seemed convenient may no longer suit its financial or commercial circumstances. Reviewing the structure periodically can therefore be just as important as choosing it in the first place.
If you’re unsure how different structures could affect your business, speaking with an accountant in Perth can help you understand the tax, reporting and financial implications before making a major structural change.